Copy this worksheet and use one row per position. Cover every position closed in the past seven days and every position still open. Value open positions at the current mark, include funding accrued to date, and label those rows as open.
| Field |
What to record |
Why it matters |
| Funding paid or received |
Net funding for each position, summed over every funding interval |
Long holds can turn a small gain into a loss |
| Position multiple at entry |
Notional-to-margin ratio at entry and at peak size |
Shows how little price movement a position can absorb |
| Liquidation distance |
Percent move from entry to liquidation price, recorded at entry |
Measures the cushion before forced closure |
| Open interest regime |
Open interest change during the hold, read together with price direction |
Separates fresh positioning from position unwinding |
| Liquidation context |
Market-wide liquidation totals in the same time window |
Shows whether the exit happened in a stressed market |
| Exit type |
Take profit, stop, manual or liquidation |
Separates planned exits from forced ones |
| Fees |
Entry and exit fees, plus any slippage you can measure |
Fees reduce the net result of every trade |
Three fields get misread more than the rest.
Funding over a long hold is a running cash flow you sum across every interval. For a long, funding paid is a cost. For a short, funding received is income, so the sign follows the side. A small price gain can flip to a loss once every interval is added up, and the rate you glanced at before entry says nothing about that total.
Position size at entry versus peak shows how far the position grew. Entry size sets the cushion you accepted. Peak size is the cushion you carried when the book was largest. If you added, those two numbers diverge, and the later one is what a sharp move had to absorb.
Liquidation distance stays the figure from entry, even if you change position size later. That preserves the cushion the trade started with. Tag liquidation exits on their own. The venue forced that close; your stop or target never fired.
The review judges your record and your process. Forecasting sits outside its scope. If perpetuals or funding still feel fuzzy, the crypto derivatives trading guide covers the definitions. The performance measurement baseline shows how to turn a week of fills into numbers you can compare across weeks.
For education only, not financial or investment advice. Crypto and trading with borrowed funds can cause substantial losses; examples do not predict future results.
Fill the table in a spreadsheet on the same day each week. A fixed time keeps the seven-day window consistent, so week-over-week comparisons measure your decisions rather than a shifting sample.
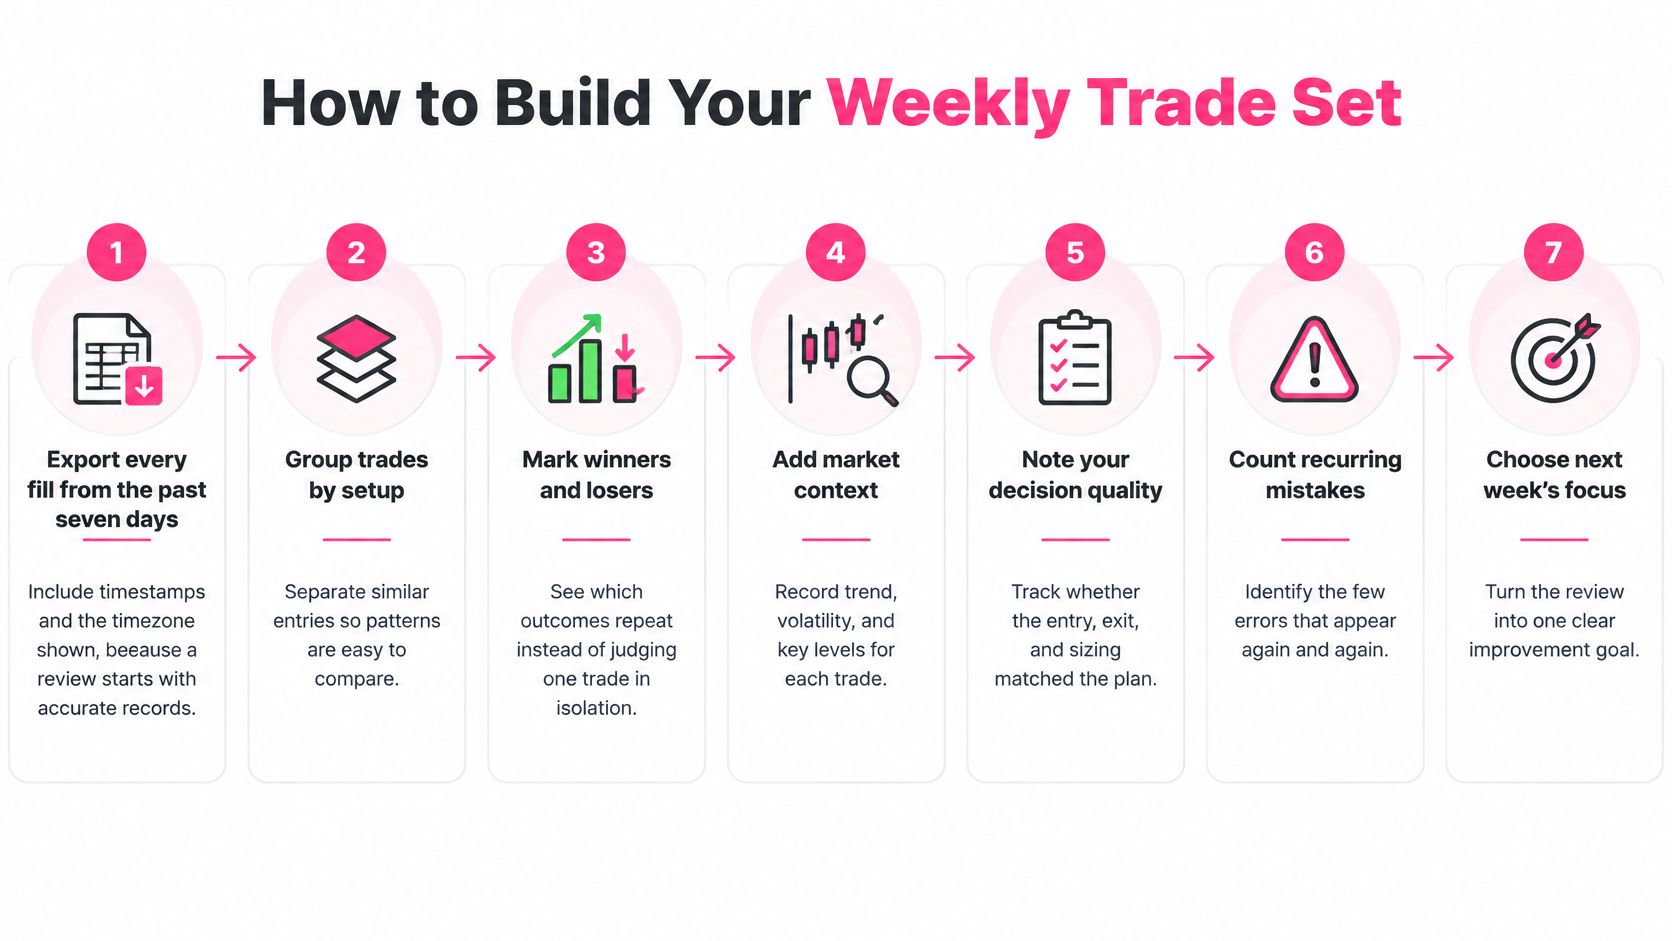
A clean set has one net result and one exit tag per position, with no blank funding line. Seven steps get you there, and the order matters: group before you score, because a funding total means nothing until you know which position it belongs to.
- Export every fill from the past seven days. Include timestamps and the timezone the venue shows. Mixed timezones break the set the moment a fill crosses midnight, and a time and frequency check only works if the clock on each fill is the same clock.
- Group fills into positions from open to flat. One position often has several entries and exits. Counting each fill as a trade overstates how many decisions you made.
- Pull the funding history across the whole hold. Funding posts on a fixed schedule, commonly every 8 hours on many venues, so check yours. The total paid or received matters more than the rate you glanced at before entry.
- Record margin and liquidation price at entry from the position screen. Memory rounds these in the direction that flatters the trade. The screen doesn't.
- Tag the exit. Use take profit, stop, manual, or liquidation. A manual flatten after you moved the stop belongs in the manual column, because the plan that placed the stop is not what closed the trade.
- Attach open interest, volume, and liquidation totals for the entry window and the exit window, each from a dated source. Without dates, next month's review can't tell a quiet hour from a cascade.
- Calculate net result as gross P&L minus fees minus funding. That single number is the score. Gross P&L is only the starting line.
If the week also includes listed equity or index options, keep those fills in a separate block. The payoff math differs enough that mixing the rows hides errors in both. A beginner guide to buying calls or puts from The Money Maniac is a useful refresher on which contract you bought before those rows sit next to perpetual swaps.
Manual entry is where most funding lines go missing, which is why step 3 exists. Thrive Pro covers the same workflow with a trade journal that takes CSV import and read-only account auto-sync, emotion and psychology tags per trade, a performance dashboard with an equity curve and R-multiples, and market data on the top 20 assets covering funding, liquidations, and open interest. After you log or sync a fill, it reviews that trade against the market around it. The plan runs a 7-day free trial, then $99 per month. Import or no import, the check stays the same: match every funding and fee figure to the venue statement before you trust a total.
You're done when every position has one net result, one exit tag, and no missing funding entry.
This example is hypothetical and illustrative. It is not a real trade and not a performance claim.
Say a long of 0.5 BTC at a hypothetical $60,000 entry, at 5x. Notional is $30,000. Posted margin is $6,000. The hypothetical exit is $61,500 after 24 hours, which covers three funding intervals at an assumed 0.01% per interval. Taker fees are an assumed 0.05% on entry notional and on exit notional. Those rates are placeholders. Your venue's schedule and rates will differ.
| Line |
Calculation |
Amount |
| Entry notional |
0.5 BTC times $60,000 |
$30,000 |
| Margin posted |
$30,000 / 5x |
$6,000 |
| Exit notional |
0.5 BTC times $61,500 |
$30,750 |
| Gross P&L |
$30,750 minus $30,000 |
$750 |
| Funding paid, 3 intervals |
0.01% of $30,000, times 3 |
$9 |
| Entry fee |
0.05% of $30,000 |
$15 |
| Exit fee |
0.05% of $30,750 |
$15.38 |
| Net result |
$750 minus $9 minus $15 minus $15.38 |
$710.62 |
| Funding paid, 27 intervals (about 9 days) |
0.01% of $30,000, times 27 |
$81 |
| Liquidation distance at 5x |
1 / 5 before maintenance and fees |
about 20% |
Exit notional is not entry notional. The exit fee uses $30,750, so it is $15.38, not another flat $15. People who copy the entry fee understate costs on a winner and overstate them on a loser.
Funding here is charged on notional, per interval. At 0.01%, one interval on $30,000 is $3. Three intervals are $9. That is small next to a $750 gross gain, which is why a one-day hold feels "free." It isn't a rule. It is this placeholder rate on this hold.
Liquidation distance at 5x is about 20% below entry before maintenance margin and fees. The 2.5% move in this example ($60,000 to $61,500) sits far from that line. Record the distance anyway. A later add, or a different rate, changes the story, and you can't reconstruct the entry cushion from the exit screenshot.
The same position held for 27 intervals, about nine days, at the same assumed rate pays $81 in funding. That is about 11% of the $750 gross gain, before fees. Nothing about the setup changed. Only the number of intervals did. That is why hold duration belongs on every row. How those venue charges are structured is covered in the crypto trading fees note.
Run the same lines on one of your own trades. Replace every placeholder with the venue's actual notional, fee, and funding print, then set net result next to gross P&L.
Price and open interest only tell you which story to test. They are not a signal by themselves.
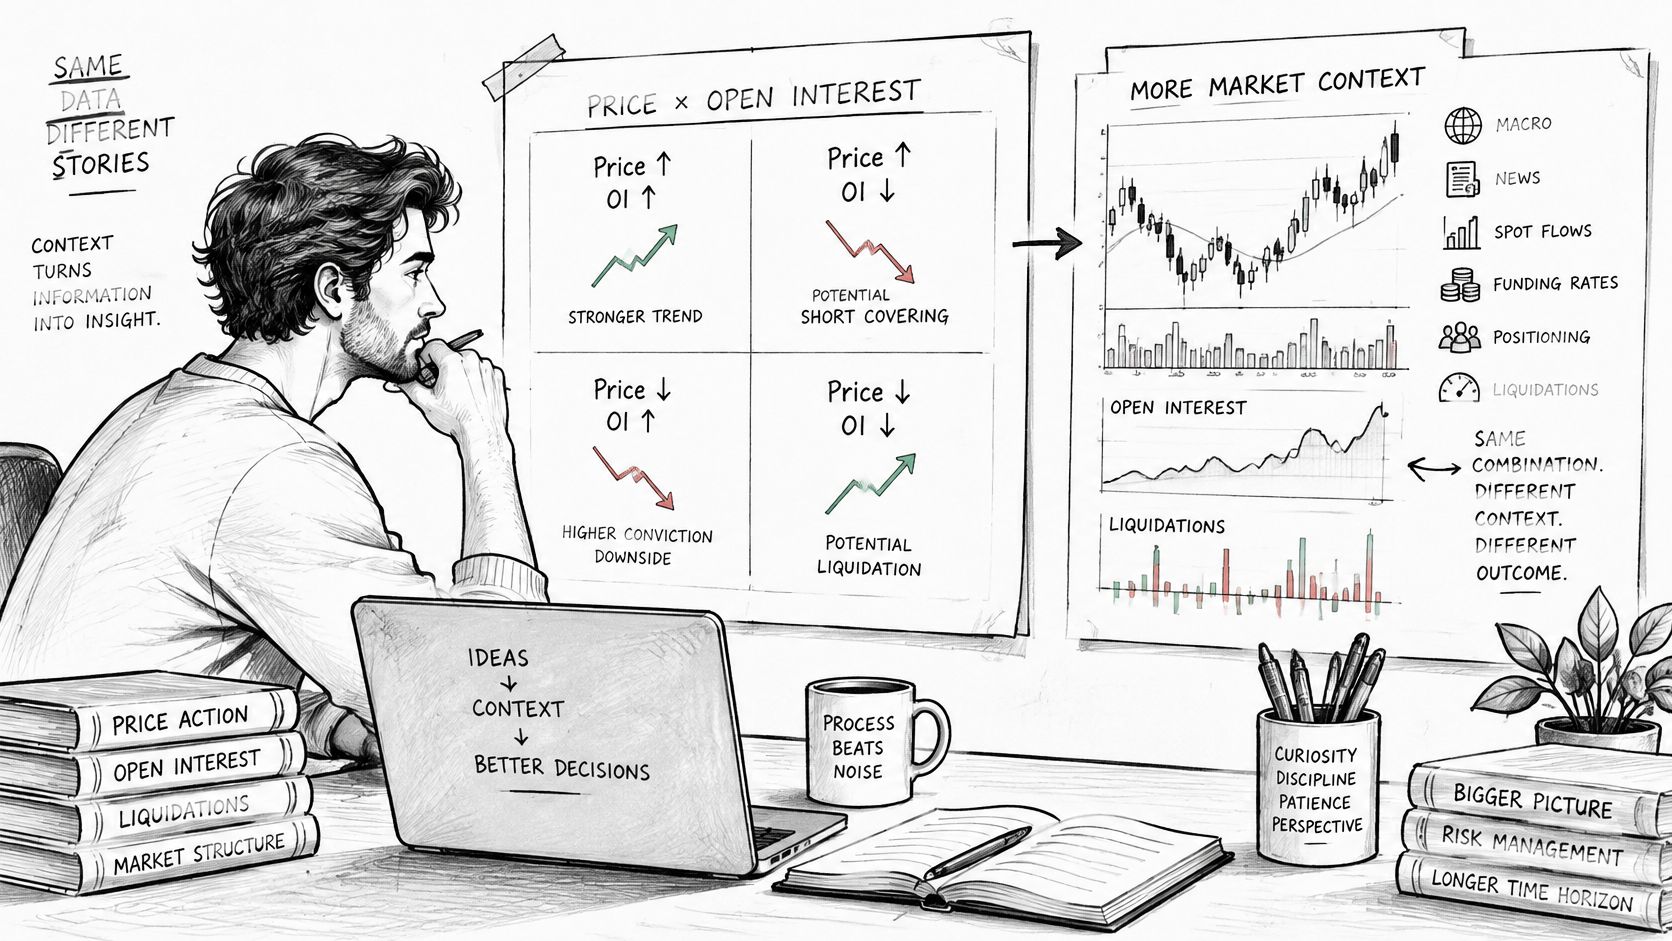
| Price move |
Open interest |
Usual reading |
Check next |
| Rising |
Rising |
New longs and building exposure |
Is funding turning high, which suggests crowding? |
| Rising |
Falling |
Shorts closing, short squeeze possible |
Were the liquidations mostly shorts? |
| Falling |
Rising |
New shorts opening or longs adding |
Are longs averaging down into the move? |
| Falling |
Falling |
Longs closing or being liquidated |
Was the split forced versus voluntary, and did funding normalize? |
As of 17 November 2026, a TMGM market note described one November 2026 liquidation wave of roughly $1.3 billion in Bitcoin long liquidations, while perpetual-futures open interest fell by about 30,000 BTC and still stayed above 330,000 BTC. The same note described subdued funding alongside those very large liquidations. That combination matters: a market can flush an enormous notional total and still carry most of its open positions.
Falling open interest can mean positions are being closed out. It can also mean exposure moved to another venue or another instrument, which exchange-level open interest cannot see. Separate perpetual swaps from dated futures and options, and read the change next to volume and basis. A drop in open interest with rising volume and a basis that does not snap back is a different week from a quiet unwind.
Tag forced closures apart from voluntary exits. Read a what triggers a margin liquidation explainer before you label an exit, because a liquidation and a panic market sell leave different footprints in the same candle. Funding can cool after a cascade without proving positioning is healthy. A dramatic liquidation total is often one stage of a longer cut in exposure, not a durable low.
Thrive automatically detects price/funding, price/OI, and funding/OI divergences, so a stretch where price climbs while open interest or funding falls gets flagged instead of missed. The funding rates and open interest playbook is the companion for reading those three series as one picture.
The video below walks through this same quadrant read on a live market week.
On each losing trade, write the quadrant from the table and whether liquidation totals were high in that window, then set the tag next to the trade's net result after funding and fees. That is what lets next week's sheet show whether losses clustered in stressed markets or in ordinary ones.
A 23 February 2026 GlobeNewswire release cited analysis of approximately 880,000 anonymized pre-trade setups and found that U.S.-based retail crypto-derivatives traders checked liquidation risk roughly twice as often as the global average in 2025. Checking more often is a habit; the review has to show whether it improves results.
R-multiple here is realized net result divided by the planned loss at entry. A $150 gain on a trade with $100 of planned risk is 1.5R. Use net result, not gross, or funding and fees inflate the R.
Log these on every trade:
- Pre-entry liquidation check: yes or no, logged before the fill, not remembered after.
- Planned stop versus actual stop: note if you widened it.
- Planned position size versus margin used: entry and any add.
- Time of day: so a bad hour doesn't hide inside a good setup.
- Emotional tag: the state you can name in one word at entry.
- Exit: voluntary or forced.
Over one month, compare average R-multiple and net result for trades with a logged pre-entry check against trades without one. Split the two groups by volatility regime, quiet versus fast. A check that only "works" in one regime is not a general control.
Small groups lie. Ten trades can show a gap that is noise, so treat any split under that size as a question for next month, not a conclusion. If the check doesn't line up with better R or a better net result, it is a ritual. You opened the liquidation panel and then took the same size.
The same method applies to the emotional tag column. A journal that stores emotion and psychology tags per trade lets you group results by the state you named at entry, and the trade journal guide on behavioral bias shows how those tags get compared against outcomes.
A risk check only matters if it changes the trade.
Pick the last seven days and finish the checklist for every closed position and every position still open. Calculate each net result the same way as the hypothetical long: gross P&L minus fees minus funding. For open trades, mark the same fields now, then compare plan with fill while the context is still fresh.
Turn the largest pattern into one rule for next week. One review is a snapshot; several consistent weeks show whether it holds. If the rule only changes because funding or fees ate the edge, write that down too, since a positive gross number can still be a bad trade.
If you want that record in one workspace, Thrive keeps the journal, performance dashboard, and funding, liquidation, and open interest context tied to each fill rather than spread across Sunday exports. Start the 7-day Pro trial on the pricing page; it is 7 days free, then $99 per month, and cancelling before the trial ends costs nothing. Pro+ is $199 per month with no trial for traders who need the broader terminal and smart money and whale feeds. Set the record up at Thrive before the next seven days close.
For education only, not financial or investment advice. Crypto and margin trading can cause substantial losses; examples do not predict future results.